Exterior Cleaning Oddington | Pressure Washing Oddington
- Residential & Commercial Cleaning Specialists
- 5-Star Rated Service & Customer Care
- Eco-Friendly Cleaning Solutions
- Expert Team Covering Oddington
Get a FREE Quote
Exterior Cleaning Oddington
Exterior cleaning and building insurance intersect in a few places, and understanding where is useful without anybody pretending to be an insurer. Routine maintenance is not generally insurable at all. Policies cover sudden and unforeseen events rather than deterioration, so growth on a roof, a blocked gutter, a green elevation or a worn driveway are the owner’s responsibility and always have been. Where it matters is the other way round. Many policies contain conditions requiring a property to be kept in a reasonable state of repair, and an insurer assessing a claim for water damage may reasonably ask whether the cause was a sudden failure or years of neglected drainage. A rotten fascia and saturated wall following a decade of overflow is a maintenance question rather than an insured event, and the distinction is where disputes arise. Records are therefore genuinely useful. Dated photographs, clearance reports and camera footage demonstrating that a system was maintained put an owner in a considerably better position than an assertion that it was. Storm damage is the clearest insured case, covering slipped tiles, displaced ridge units and wind-lifted flashings, and a prompt inspection after severe weather supports that. Contractors’ insurance is a separate matter, and treatment liability is the cover that applies to a damaged surface. None of it is complicated, and very little of it is discussed until something has already gone wrong. It is also worth saying plainly that none of this amounts to advice about a particular policy. Cover differs enormously between insurers and between products, exclusions matter more than headline descriptions, and the only reliable answer to any specific question is the one the insurer gives. Policies vary considerably, and the insurer remains the authority on any specific question. Stewart Exterior Cleaning provides the documentation either way. Households in Oddington searching exterior cleaning near me should keep the reports.
Pressure Washing Oddington
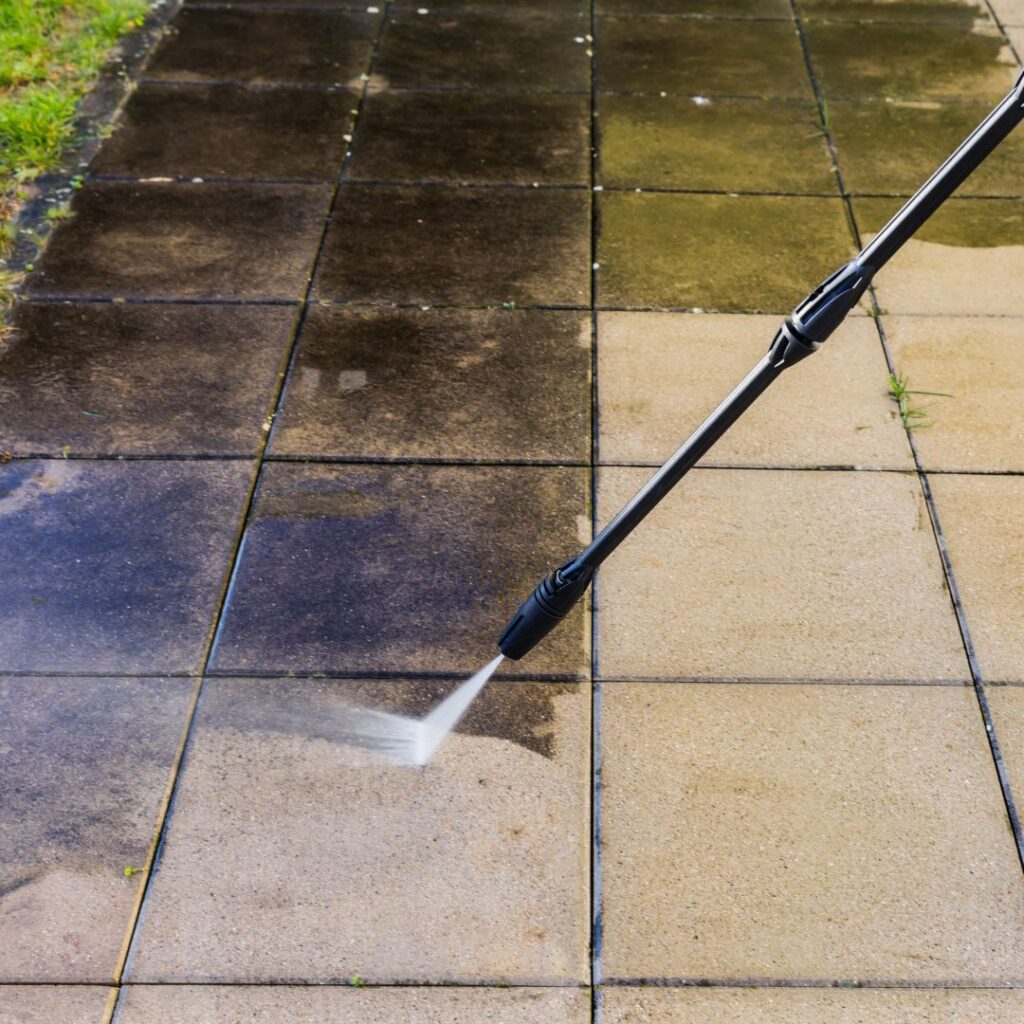
Damage caused during mechanical cleaning is a contractor’s liability rather than a household insurance matter, and knowing which policy applies to what saves a good deal of confusion later. Public liability cover deals with injury caused to third parties and with damage to their property, and it is what most people have in mind when they ask whether a firm is insured at all. It is entirely necessary and it is not, on its own, sufficient for this kind of work. Treatment liability is the cover that actually matters here. It applies to the surface actually being worked on, which public liability generally excludes, and it is the policy that actually responds when a lance has cut striping into a driveway, stripped the colour skin from pattern-imprinted concrete or scoured out mortar joints. It is also the cover most often absent from a cheap quotation. Photographs taken at the survey stage are what make any claim workable at all, since a cleaned surface reveals everything the dirt was concealing and, without a dated record, arguments about pre-existing exposed aggregate or previous striping become unresolvable. Damage caused to a neighbouring property by overspray or run-off falls under public liability instead, which is another argument for protection being taken seriously. And silt driven into the drainage during cleaning, blocking a shared gully for two households, is exactly the sort of avoidable incident that tests both policies at once. Asking about cover in general terms rarely produces a useful answer, since almost every firm carries something. A certificate takes only a moment to produce and settles the whole question entirely, which is precisely why any reluctance to show one is itself informative. Anyone in Oddington booking pressure washing near me should ask specifically for treatment liability rather than for insurance as a whole.
Are you based in Oddington or the Surrounding Areas?
Patio & Driveway Cleaning Oddington
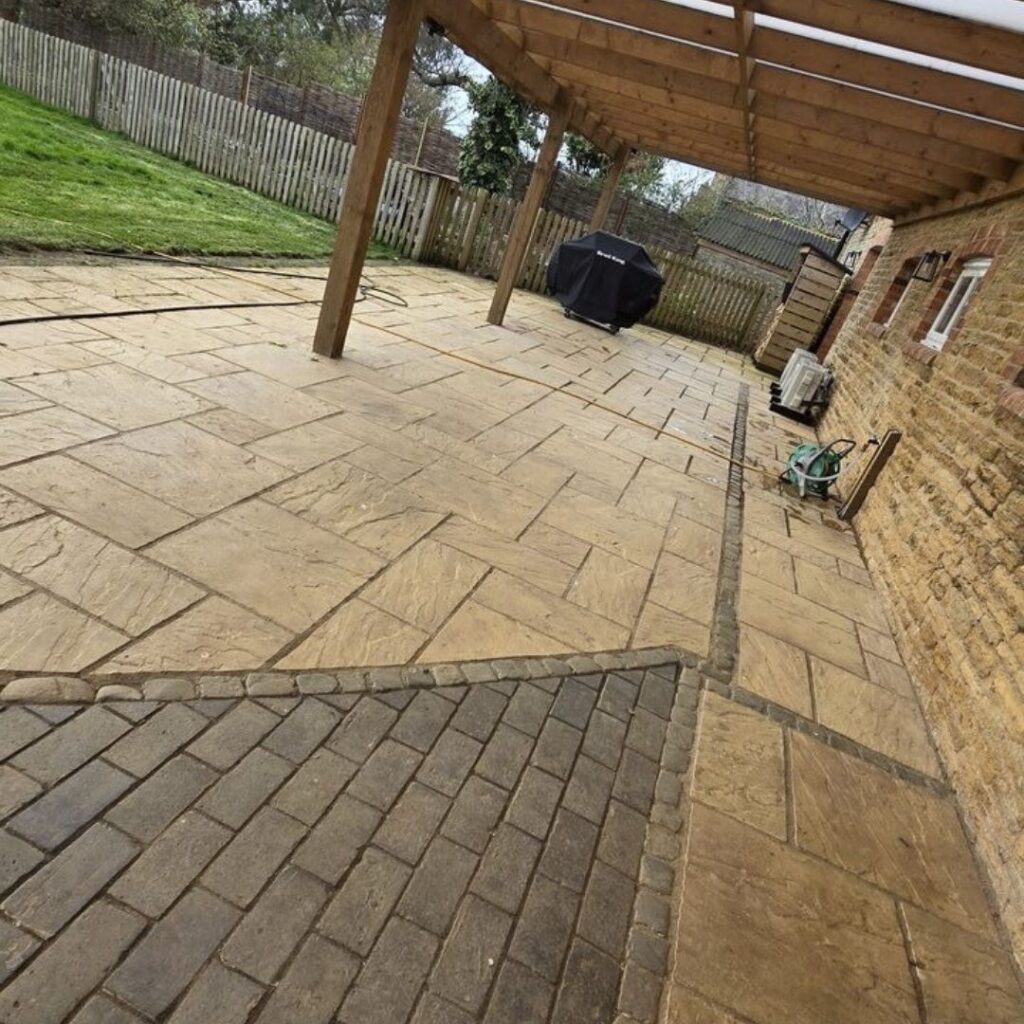
Driveway damage divides into what an owner simply absorbs, what a contractor’s insurer covers and what a household policy might conceivably reach, and the three categories are quite separate. Ordinary wear and tear is the owner’s to absorb. Faded pigment, exposed aggregate on ageing concrete, chipped arrises from years of traffic and settlement from a poorly compacted sub-base are all deterioration rather than events, and no policy covers deterioration. Contractor damage is squarely the contractor’s to put right. Striping cut into a surface, a lost colour skin, scoured joints left unfilled or a cloudy finish from sealer applied to damp paving are all matters for treatment liability cover, and they are why dated photographs taken before work matter so much. Sudden and identifiable events may well be insured. A vehicle impact, a fallen tree, subsidence in some circumstances, or damage arising from a burst pipe or a failed drain are the sorts of thing a household policy addresses, though the terms vary and the insurer decides. Flood damage forms its own category entirely and depends completely on the terms of the particular policy held. What sits in between those two categories causes most of the difficulty: a driveway that has failed because a soakaway stopped working over several years is deterioration, while one that failed because a drain collapsed suddenly may not be. The practical conclusion is that documentation costs nothing and settles most of it. A dated set of photographs taken before any work, kept alongside the survey notes, distinguishes wear from damage and old damage from new, and it is the one thing that cannot be produced retrospectively. None of this is advice on any particular policy, and the terms differ considerably between insurers. Homeowners in Oddington booking driveway cleaning near me should have the starting condition photographed regardless.
Roof Cleaning Oddington
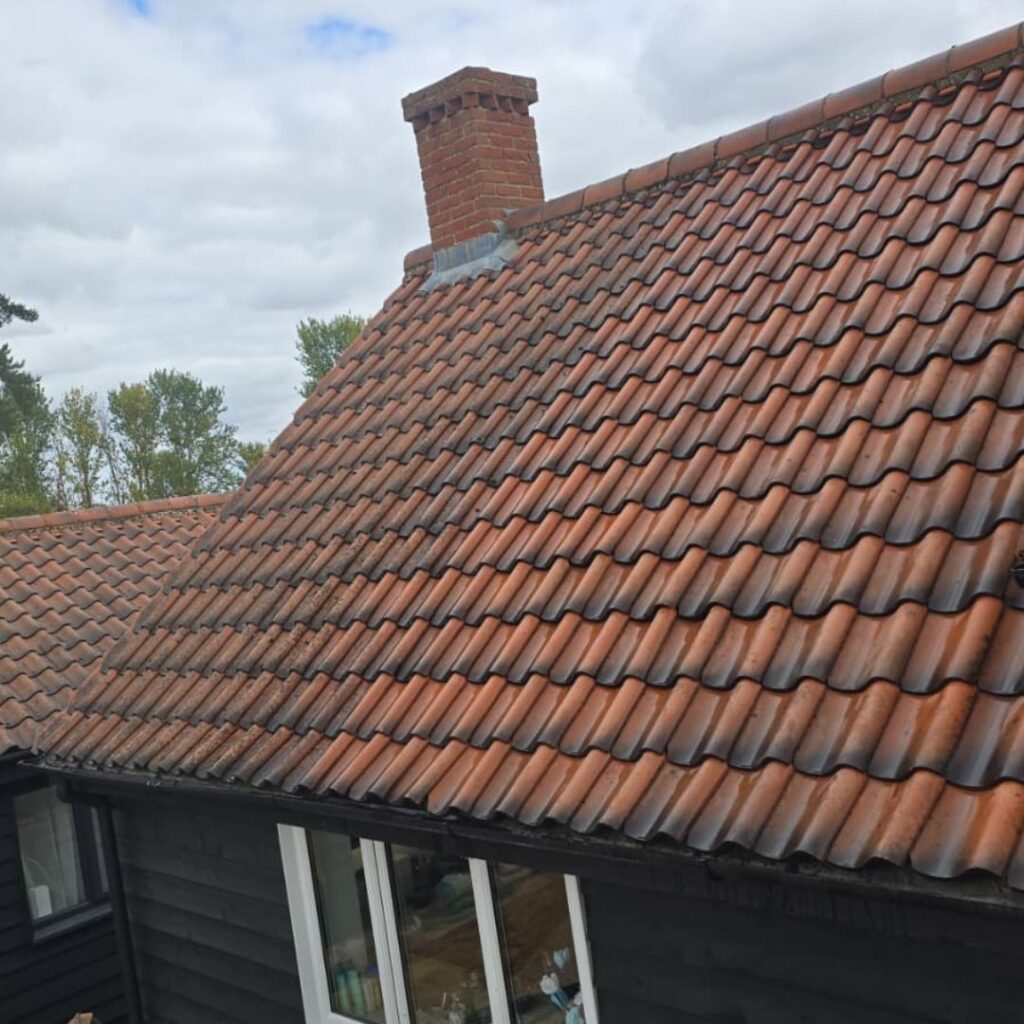
Roof damage is where insurance questions arise rather more often than anywhere else, and the distinction that matters throughout is between an event and a process. Storm damage is the classic insured case of all. Slipped or displaced tiles, lifted ridge units, damaged flashings and debris impact following high winds are sudden, identifiable and generally covered, subject to the policy terms and to whatever wind speed threshold the insurer applies. Gradual deterioration is not. A covering that has been holding moisture in a saturated moss mat for fifteen years, opening its laps through successive frosts, is not the subject of a claim, and neither is the underlay that has rotted as a consequence. The difficulty arises at the point where the two meet. A tile that slipped in a gale may have slipped because the nail had corroded and the growth around it had been lifting it for years, and an insurer assessing that will consider whether the property was reasonably maintained. Which is precisely where documentation earns its place. A dated inspection report with photographs of ridge bedding, flashings and verge pointing, showing a covering in maintained condition before the event, is considerably more persuasive than a recollection. A prompt inspection following any storm supports a claim and, rather more usefully, prevents a small displacement from quietly becoming water ingress over the following months. It is worth adding that none of this is advice about any particular policy, since terms differ considerably between insurers and the wording around storm damage in particular varies. The insurer decides, and the documentation simply puts an owner in a position to answer their questions properly. It is also the cheapest thing on any roof quotation and the item most often left out of one. Anyone in Oddington searching roof cleaning near me should treat the inspection report as well worth keeping.
Solar Panel Cleaning Oddington
Solar installations sit somewhat awkwardly between building insurance, contents cover and the manufacturer warranty, and knowing which of them applies to what is worth establishing early. Most household policies treat a roof-mounted array as forming part of the building, though it is worth confirming rather than assuming, and some insurers require notification that an array has been fitted at all. Storm and impact damage is generally the insured case here. Wind lifting a panel, hail cracking glass or debris striking the array are sudden events, and a prompt inspection with photographs supports any claim. The manufacturer warranty covers the modules themselves against defect and, typically, against a specified rate of output degradation, and it almost invariably excludes damage caused by pressure washing, abrasive cleaning or walking on the panels. That exclusion is precisely why the cleaning method is what it is. Contractor liability covers any damage caused during a cleaning visit, which is why treatment liability cover matters here as much as anywhere. Soiling itself is nobody’s liability at all, under any policy. Lost generation from a dirty array is a maintenance matter and always has been. Generation records are the genuinely useful documentation here, since they establish what the system was actually producing before any event occurred. The warranty paperwork is worth locating early, particularly on a property bought with an array already installed, since the terms determine what is covered and for how long and are frequently mislaid between owners. None of this is advice on any specific policy, and the insurer and the manufacturer are the authorities on their own terms. Keeping the installation certificate with the rest of the property paperwork is a small habit that saves a good deal later. Owners in Oddington should confirm with their insurer how the array is treated under their policy.
Our Customers Say Everything there is to know about us
EXCELLENTTrustindex verifies that the original source of the review is Google. Fantastic service through out! Our roof looks brand new! Decided to also get the driveway done after seeing the results of first job and what a difference! All for a reasonable price as well. Definitely highly recommend 5*Posted on GoogleTrustindex verifies that the original source of the review is Google. Brendan of Stewart Exterior Cleaning was superb. He obviously knows a lot about looking after the exterior of a property and when he visited to clean our gutters, he clearly explained what was going on and gave excellent advice for the future. He was also friendly and enthusiastic, and gave us the sense he enjoys his work and taking care of his customers. He also mentioned some of his company's other services such as landscape gardening, which probably explains why he has so much expertise. But as it was winter and just before Christmas when he visited, it wasn't the right time for things for the garden, but we'd like to have him back in the spring, so he's probably got a customer for life now! Thanks so much, Brendan – it's very obvious why your business is thriving and we'll be back in touch in the future!Posted on GoogleTrustindex verifies that the original source of the review is Google. Brendan was very helpful and informative, he was quick and efficient in completing the job while answering any questions I had, I would definitely recommend his servicesPosted on GoogleTrustindex verifies that the original source of the review is Google. Returning customer of Stewart Exterior Cleaning. Brendan did a gutter clear for us recently and came back today to carry out a repair caused by high winds. Very friendly servicePosted on GoogleTrustindex verifies that the original source of the review is Google. Great service, roof looks newPosted on GoogleTrustindex verifies that the original source of the review is Google. Great service, couldn’t be happier with the end result. We initially had Brendan in to pressure wash and re-sand our driveway and after seeing the excellent job he did, we decided to have the roof and gutters cleaned as well. The transformation has completely refreshed our home and added fantastic curb appeal. Reliable, friendly, and great value for the service provided thanks again, Brendan!Posted on GoogleTrustindex verifies that the original source of the review is Google. Excellent job completed by Brendan. Was prompt and went above and beyond - given that there wasn’t a useable tap on sight! Also advised what do do after cleaning with regards to paving slabs. Would highly recommend, very excellent price and top notch service. Thank you BrendanPosted on GoogleTrustindex verifies that the original source of the review is Google. Excellent job done in a most friendly and efficient manner. Would highly recommend Brendan and his company to anybody looking to have their gutters cleared and fascia’s cleaned. Well done Stewart Exterior Cleaning.Posted on GoogleTrustindex verifies that the original source of the review is Google. I spotted Brendan working at neighbours property and asked him for a quote to pressure wash my pathway and patio. We agreed a price and the work was carried out a few days later. Brendon is hardworking, friendly and diligent and I’m very happy with the outcome and overall experience.Posted on GoogleTrustindex verifies that the original source of the review is Google. Fantastic service from Stewart Cleaning Ltd. Great work, tidy and very accommodating. Would definitely recommend and will definitely be using these guys again. Thank you! Noticed my dirty windows and even cleaned them despite it not being part of the booked job! Many many thanks.
Gutter Cleaning Oddington
Water damage traced back to guttering is the most common point at which exterior maintenance and insurance meet, and the outcome usually turns on how long the problem has been running. A sudden and identifiable failure may well be covered. A downpipe sheared off in a storm, a section brought down by a falling branch or damage from an identifiable event is the sort of thing a policy addresses. Gradual overflow over a period is quite a different matter. Water that has been spilling from a blocked run for two winters, rotting a fascia, saturating masonry and eventually showing as damp on an internal wall, is deterioration arising from maintenance rather than a sudden event, and most policies say so plainly. That is the argument for keeping a schedule stated in terms an insurer would recognise. Dated clearance records with camera footage showing the runs cleared demonstrate that the system was being maintained, which matters if a genuine sudden failure ever does occur. The awkward middle ground is where an insurer concludes that a blockage caused the escape of water and asks how long the run had been left. None of this amounts to a reason to insure guttering, which nobody does, and all of it is a reason to keep hold of the receipts and the camera footage. Policies differ, and the insurer determines any specific case. It is worth repeating that this is general rather than specific, since the wording differs considerably between policies and the treatment of gradual damage in particular is not uniform. The insurer is the authority on any individual claim, and the records simply allow an owner to answer whatever is asked. The camera footage in particular is the one piece of evidence that cannot be produced after the event. Householders in Oddington should keep clearance records with the rest of the property documentation.

Render Cleaning Oddington
Damage to a rendered elevation raises insurance questions rather more often than most exterior work, because the wrong cleaning method causes damage that is both immediately obvious and expensive to remedy. Contractor damage is much the clearest case of the three. Pale scoured patches, exposed base coat and a hard edge where a pressure-washed area stops are permanent, the remedy is re-rendering the elevation, and the cover that responds is treatment liability rather than public liability. A firm without it is not in a position to put right what it has done. Photographs taken at the survey stage are what make that workable, since a wall that has been previously damaged looks much the same as one damaged last week once the growth has been removed, and a dated record separates the two. Storm damage to an elevation may be insured. Impact from debris, particularly on a thin coat over external wall insulation where a solid wall would be unmarked, is a sudden event. Gradual deterioration is not insured at all. Crazing from years of saturation, hollow sections from a wall that could never dry, and colonisation of any degree are maintenance matters. Water ingress traced to a breached finish sits somewhere between the two and depends entirely on what caused the breach in the first place. As elsewhere, none of this constitutes advice about a particular policy, and cover for water ingress through a render system varies considerably between insurers. What does not vary is the value of a dated record of the wall before anybody worked on it. The pump pressure quoted is the other figure worth having in writing, for much the same reason. Anyone in Oddington comparing render cleaning near me should ask to see a treatment liability certificate rather than a public liability one alone.